![All Sorted Logo - Rectangle - 2000 x 1000.jpg]](https://knowledge-base.allsorted.au/hs-fs/hubfs/All%20Sorted%20Logo%20-%20Rectangle%20-%202000%20x%201000.jpg?height=50&name=All%20Sorted%20Logo%20-%20Rectangle%20-%202000%20x%201000.jpg)
ℹ️ General Information Only: This guide is provided for general educational and informational purposes only and does not constitute personal financial, taxation, legal, or social security advice. Government rules change frequently and individual circumstances vary—always verify requirements directly with Services Australia, the ATO, or a registered tax professional before acting.
Table of Contents
Quick Reference: Official DSS, DEWR & Legislative Citations
1. DSS Social Security Guide Section 3.11.3.70: Self-Employment & Mutual Obligation Requirements
2. DSS Social Security Guide Section 3.11.3.20: The "Sufficient Work Test"
5. Can a Participant Prepare Their Own SU580 Form, or Must They Use a Bookkeeper?
Self-employed Participants in Inclusive Employment Australia (IEA), Disability Employment Services (DES), and Workforce Australia sometimes ask a fair question:
"Where does it state in the Department of Social Services (DSS) guidelines that a Profit and Loss (P&L) statement is mandatory evidence for my Mutual Obligation Requirements? Why can't I just declare the hours I worked in my business or report my gross fortnightly income?"
The short answer is that under Australian social security law, self-employment hours cannot be verified by time worked alone. Instead, Services Australia (Centrelink), the Department of Social Services (DSS), and the Department of Employment and Workplace Relations (DEWR) are legally required to apply the "Sufficient Work Test"—which calculates your recognised hours of work by dividing your net business profit (gross business income minus allowable business expenses) by the National Minimum Wage.
Because neither your Employment Services Provider nor Services Australia can legally determine your net profit without subtracting your business expenses from your gross revenue, an interim Profit and Loss Statement—specifically the official Services Australia Centrelink SU580 Profit and Loss Statement and/or a signed statement of net earnings prepared by an accountant or registered bookkeeper—is mandatory documentary evidence.
Below is the section-by-section breakdown of the DSS Social Security Guide, the Social Security Act 1991, and the DSS and DEWR Employment Services Documentary Evidence Guidelines, with direct links to the official Australian Government sources.
Quick Reference: Official DSS, DEWR & Legislative Citations
- DSS Social Security Guide — Section 3.11.3.70 (Self-employment): Applies to both DSS (DES/IEA) and Workforce Australia. Self-employment only satisfies Mutual Obligation Requirements if net business income earned equals or exceeds the required hours multiplied by the National Minimum Wage. Official Reference: DSS Social Security Guide Section 3.11.3.70
- DSS Social Security Guide — Section 3.11.3.20 (Employment — Sufficient Work Test): When a Participant is self-employed, recognised hours of work (including for Workforce Australia Points Based Activation System points and part-time exemptions) are calculated by dividing net profit received by the National Minimum Wage. Official Reference: DSS Social Security Guide Section 3.11.3.20
- DSS Social Security Guide — Section 4.7.1.20 (Assessment of income for sole traders & partnerships): Sole trader income is never assessed via fortnightly wage reporting; it is assessed on net profit after allowable expenses using interim Profit and Loss Statements (Form SU580). Official Reference: DSS Social Security Guide Section 4.7.1.20
- Social Security Act 1991 (Cth) — Sections 1074 & 1075 (Business income & permissible reductions): Establishes the statutory rule that ordinary income from a business is assessed net of permissible business expenses over a representative period. Official Reference: Social Security Act 1991 (Federal Register of Legislation)
- DEWR Workforce Australia Guidelines — Part B: Workforce Australia Services (Unsubsidised Self-Employment): Requires Providers to obtain a Profit and Loss Statement, a signed statement of earnings from an accountant and/or registered bookkeeper, or ATO records verifying that net business income meets the National Minimum Wage. Official Reference: DEWR Workforce Australia Guidelines (Part B)
- DSS Program Guidelines — Disability Employment Services / IEA Program Guideline (Unsubsidised Self-Employment): Requires dated documentary evidence in the form of a Profit and Loss Statement, a signed statement of earnings from an accountant and/or registered bookkeeper, or ATO records confirming net personal income. Official Reference: DSS Disability Employment Services Program Guideline
- Services Australia Official Form — Form SU580 (Profit and Loss Statement): The official Services Australia form required to verify sole trader income and allowable business deductions where a tax return does not reflect current trading. Official Reference: Services Australia Form SU580 (Profit and Loss Statement)
1. DSS Social Security Guide Section 3.11.3.70: Self-Employment & Mutual Obligation Requirements
In the Department of Social Services (DSS) Social Security Guide—which is the binding policy manual governing Mutual Obligation Requirements across both Workforce Australia and Disability / Inclusive Employment Australia for JobSeeker Payment, Youth Allowance (Other), Parenting Payment, and Special Benefit—Section 3.11.3.70 (Self-employment, including through Workforce Australia – Self-Employment Assistance) sets out when self-employment counts toward a Participant's Job Plan.
- Official Reference: DSS Social Security Guide — Section 3.11.3.70 (Self-employment)
What Section 3.11.3.70 States:
- Hours Worked Alone Are Not Sufficient: Outside of an approved, time-limited Workforce Australia – Self-Employment Assistance (SEA) coaching period, a Participant cannot satisfy their Mutual Obligation Requirements (or claim paid-work points under Workforce Australia's Points Based Activation System) merely by spending hours working in an unprofitable or low-revenue business.
- The Minimum Wage Net Income Rule: For Participants with part-time Mutual Obligation Requirements—including Participants with a Partial Capacity to Work (15 to 29 hours per week), Principal Carer Parents, and Participants aged 55 and over—Section 3.11.3.70 explicitly states that they fully meet their Mutual Obligation Requirements through self-employment only if:
"They undertake at least 30 hours per fortnight of self-employment, where the income earned from self-employment is equivalent to or above 30 hours work at the minimum wage."
- Consequence of Earning Below Minimum Wage Net Profit: If the Participant's net business profit is below the National Minimum Wage equivalent for their required hours, DSS policy states that self-employment alone cannot satisfy their Mutual Obligation Requirements, and they must look for alternative paid work or complete other compulsory activities in their Job Plan.
Because "income earned from self-employment" under the Social Security Act 1991 means net profit after business expenses (not gross sales or raw hours worked), a Profit and Loss Statement is the only way to verify whether a Participant meets Section 3.11.3.70.
2. DSS Social Security Guide Section 3.11.3.20: The "Sufficient Work Test"
Whenever a Participant in Workforce Australia or Inclusive Employment Australia / DES asks to have self-employment reduce or satisfy their Mutual Obligation Requirements, Services Australia and Employment Services Providers must apply the Sufficient Work Test defined in Section 3.11.3.20 (Employment).
- Official Reference: DSS Social Security Guide — Section 3.11.3.20 (Sufficient Work Test)
How the Sufficient Work Test Calculates Self-Employed Hours:
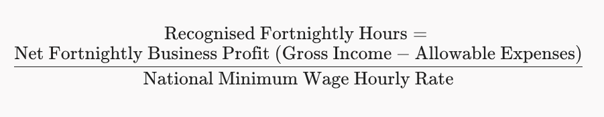
- Practical Example: Suppose a self-employed Participant works 40 hours in a fortnight, collects $1,200 in gross customer invoices, and spends $800 on business expenses (fuel, stock, materials, insurance). Their net business profit is $400 for the fortnight.
- Under DSS Section 3.11.3.20, their recognised hours for Mutual Obligation compliance (and Workforce Australia PBAS paid-work points) are calculated by dividing $400 by the National Minimum Wage—not the 40 hours physically worked, and not the $1,200 in gross turnover.
- Without a Profit and Loss Statement separating gross sales from allowable business expenses, neither the Employment Services Consultant nor Services Australia can legally calculate net profit under the Sufficient Work Test.
3. DSS Social Security Guide Section 4.7.1.20 & Social Security Act 1991 (s 1074 & s 1075): Mandatory Interim Profit and Loss Statements
Some self-employed Participants ask why they cannot simply report their gross invoices each fortnight the way a PAYG wage employee reports payslips. DSS Social Security Guide Section 4.7.1.20 (Assessment of income for sole traders & partnerships)—backed by Sections 1074 and 1075 of the Social Security Act 1991—specifically prohibits assessing sole traders like wage employees and mandates interim Profit and Loss Statements.
- Official References:
What Section 4.7.1.20 Requires:
- Net Business Income Rule:
"Income from a sole trader or partnership business is the net amount: AFTER allowable expenses for the cost of running the business, and BEFORE income tax and other personal deductions."
- Mandatory Interim Profit and Loss Statements (Form SU580): Where a business has recently commenced, where income has changed, or where a lodged annual tax return does not reflect current trading, Section 4.7.1.20 requires interim Profit and Loss Statements (specifically the official Services Australia SU580 Profit and Loss Statement or an accountant/bookkeeper-prepared Profit and Loss Statement) to establish the annualised rate of net business income.
4. DSS & DEWR Employment Services Program Guidelines: Documentary Evidence for Unsubsidised Self-Employment
In addition to Centrelink's income assessment rules, Employment Services Providers delivering Workforce Australia (under DEWR) and Inclusive Employment Australia (IEA) / Disability Employment Services (DES) (under DSS) must comply with strict contractual Documentary Evidence Guidelines for Unsubsidised Self-Employment (meaning normal sole-trader or independent-contractor self-employment where no government wage subsidy is paid).
- Official Program Guideline Downloads:
What the DSS & Workforce Australia Documentary Evidence Rules State Verbatim:
When an Employment Services Provider is required to verify a self-employed Participant's net earnings and hours (over a 4, 12, or 26-week period) to confirm that the business has generated sufficient personal income (net of business expenses) to achieve the National Minimum Wage rate, both the DEWR Workforce Australia Guidelines (Part B) and the DSS Program Guidelines specify that dated documentary evidence must be obtained from the Participant in one or more of the following forms:
- "Sales records, contracts with clients or contracts of employment and a statement from a Certified Practising Accountant or Certified Accountant (for example a Profit and Loss Statement) relating to the Participant's business for the 4, 12 or 26 Week Period;"
- "Signed and dated statement of earnings from an accountant and/or registered bookkeeper for the 4, 12 or 26 Week Period; or"
- "Copy of records from the Australian Taxation Office (ATO) for the 4, 12 or 26 Week Period verifying that the Participant has generated sufficient personal income (net of business expenses) to confirm the National Minimum Wage rate has been achieved."
5. Can a Participant Prepare Their Own SU580 Form, or Must They Use a Bookkeeper?
While a Participant cannot refuse to provide a Profit and Loss Statement (because net profit after business expenses must be verified under both the Social Security Act 1991 and the Sufficient Work Test), Participants have two compliant pathways depending on how their verification is being processed:
- Pathway 1 — Provider-Funded or Bookkeeper-Verified Profit & Loss Statement (Fastest & Fully Audit-Compliant): Many Employment Services Providers fund the cost of having an independent, registered bookkeeper prepare a verified Profit and Loss Statement (alongside a pre-filled Centrelink SU580 form). Under the DSS and DEWR Documentary Evidence Guidelines quoted above, a signed and dated Profit and Loss / statement of net earnings from a registered bookkeeper or accountant immediately satisfies the Provider's audit requirements AND gives the Participant an accurate SU580 PDF to upload to their Centrelink online account via myGov.
-
Pathway 2 — Self-Prepared Services Australia Form SU580 (Wait for Centrelink Assessment): Services Australia does not force a sole trader to pay an accountant to fill out Form SU580 (Profit and Loss Statement). A Participant may prepare and sign their own SU580 (and Form Mod F if newly self-employed), attach their supporting tax invoices and expense receipts, and lodge it directly with Services Australia via myGov (or use All Sorted's Self-Service SU580 Portal). However, until Services Australia processes that SU580 and updates the Participant's verified self-employment income on the government system—or until the Participant provides compliant documentary evidence under the Provider Guidelines—their Employment Services Provider cannot credit unverified self-employment hours toward their Mutual Obligation Requirements.
6. Summary
| Common Question | Official DSS / Services Australia Rule |
| "Can I just declare the hours I worked in my business to meet my Mutual Obligations?" | No. Under DSS Guide 3.11.3.70 and 3.11.3.20, self-employment hours are calculated by dividing your net business profit by the National Minimum Wage (Sufficient Work Test). |
| "Can I just show my gross sales invoices or bank deposits without expenses?" | No. Under Social Security Act 1991 s 1075 and DSS Guide 4.7.1.20, sole trader income must be assessed net of allowable business expenses via a Profit and Loss Statement (SU580). Reporting gross sales as employment income causes inaccurate assessments and potential Centrelink debt or payment suspension. |
| "Why does my Employment Consultant need a Bookkeeper-verified P&L Statement?" | Under the DSS / DEWR Documentary Evidence Guidelines, Employment Services Providers are legally required to hold a verified Profit and Loss Statement (or statement of net earnings from an accountant or registered bookkeeper) to credit self-employment toward your Job Plan and Mutual Obligations. |
| "How can I get my Profit and Loss Statement or Centrelink SU580 sorted quickly?" | You can get started online in minutes via the All Sorted Profit & Loss Portal. |
Important Disclaimer — General Information Only
The information contained in this article is provided by All Sorted Business Services ("All Sorted") as a general guide and for educational purposes only. It has been prepared without taking into account your individual objectives, personal financial situation, business structure, or specific social security circumstances.
Not Financial, Legal, or Tax Advice: Nothing in this article should be construed or relied upon as professional legal, financial, taxation, or social security entitlement advice. Because every Participant's circumstances are unique, you should always seek independent advice from a qualified accountant, registered Tax or BAS Agent, financial counsellor, or directly from Services Australia (Centrelink), the Department of Veterans' Affairs (DVA), or the Australian Taxation Office (ATO) before making any decisions or lodging official forms.
Currency of Information & No Warranty: While All Sorted endeavours to ensure the accuracy of the information at the date of publication, Australian taxation laws (including the Income Tax Assessment Act 1997), social security legislation (including the Social Security Act 1991), and government agency policies, thresholds, and forms change periodically without notice. Over time, parts of this article may become superseded or out of date. All Sorted makes no warranties or representations—express or implied—as to the accuracy, currency, completeness, or reliability of the content, and to the maximum extent permitted by Australian law, accepts no liability for any loss, overpayment debt, penalty, or damage arising from any error, omission, or reliance on this information.
No Government Affiliation: All Sorted Business Services is an independent Australian bookkeeping and software provider and is not affiliated with, endorsed by, or part of Services Australia, Centrelink, the ATO, or any other Australian Government department.